A $505,500 payout for 'lost earnings' was taxed as an ETP
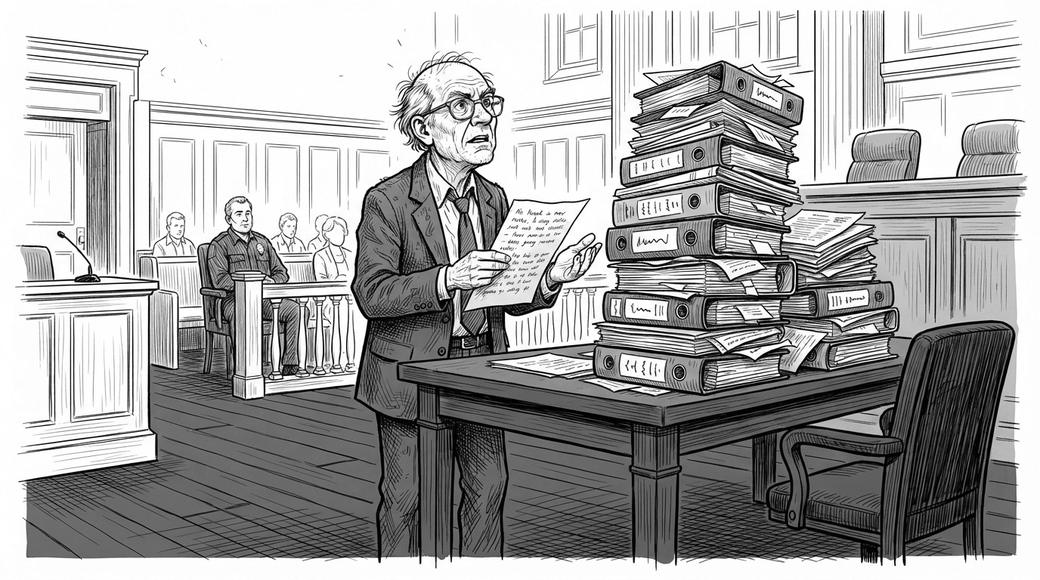
In 2000, aged 55, David Stark accepted a job with Indigenous Business Australia and turned down another offer. In December 2001 his employment was terminated. He sued in the Supreme Court of Queensland for breach of his employment terms and for misleading or deceptive conduct, claiming the job offer had led him to give up the other one and that his age and outdated skills then kept him out of work.
A trial began in February 2009 and was adjourned for mediation, where the case settled. The deed paid him $555,500: $50,000 for general damages and $505,500 'in respect of the claim by Mr Stark for lost earnings'. The agency admitted no liability, and he released it from all claims connected with his employment and its termination.
The tax office said the $505,500 was an employment termination payment, or ETP. It later assessed the payment as ordinary income instead, which it conceded was wrong, and the Administrative Appeals Tribunal held it was an ETP. Representing himself, Mr Stark argued it was compensation for a wrong or injury done to him, and so not taxable at all, or else a genuine redundancy payment.
The Federal Court rejected each argument. The payment 'followed on' from his dismissal: without the termination there would have been no claim, so it was received in consequence of it. It was not compensation for an injury, because a settlement made without any admission or finding concerns only an alleged wrong; the money was paid for the wide release he gave. And on his own account he was dismissed after a disagreement, not because his job was genuinely redundant. The Tribunal's ruling stood: the payment was an ETP, which is taxed concessionally. He was ordered to pay the costs of the appeal.
How a settlement is described, and what claims it settles, affects how it is taxed. A payment for releasing claims connected with the end of your job will often be treated as an ETP, so check the tax treatment with an adviser before you sign.
The ETP caps and tax rates have changed since 2009. The case decided how the payment was characterised, not the amount of tax; current figures are in the tax section of this page.
A published decision of the Federal Court of Australia, retold in plain English. Lawcaptain did not act in this case. Every outcome depends on its own facts. General information, not legal advice about your situation.
Dismissed? Know what your case is worth.
The Employment Case Review checks your facts against real decisions like this one.
For employees in the Fair Work system. Employed by a WA sole trader, partnership, State agency or council? The review isn't for you — see the WA state system.
Settlement deeds
 She signed a deed in 2008, then spent a decade trying to undo itFull Court of the Federal Court of Australia · 13 November 2024Read the case study
 Told his job was redundant, he signed an 8-page deal on the spotFair Work Commission · 8 July 2025Read the case study
 He agreed the money, but not the release, so there was no dealFair Work Commission · 11 July 2023Read the case study